Author: Financial Advisor
-
The Six-Month Emergency Fund Everyone Recommends Is an Expensive Psychological Trick. Here Is Why.
Introduction “Keep six months of expenses in cash so you will not have to sell investments at the worst possible time.” This sounds unquestionably prudent. But what exactly would that “worst possible time” cost? And how much are you paying while waiting for it? The Price of Safety You finally decided to take care of…
-
The Arbitrarily Invented Retirement Number
“I would retire if I had $5 million.” The number sounds precise, but it represents a feeling, not a calculation. No expected spending, taxes, housing costs, or withdrawal rate have been established. Core question: What monthly lifestyle are you trying to finance, where do you plan to live, what asset allocation do you expect to…
-
It Is Not About Money Until We Remove Money
The Invisible Money Driver in Action Imagine the situation. You are discussing your plans for the next five or ten years with an acquaintance. “I’m getting a bit bored with my current job. Perhaps I should change careers. Nursing might be good. It is easy to find a job.” Why change careers? “Well, my current…
-
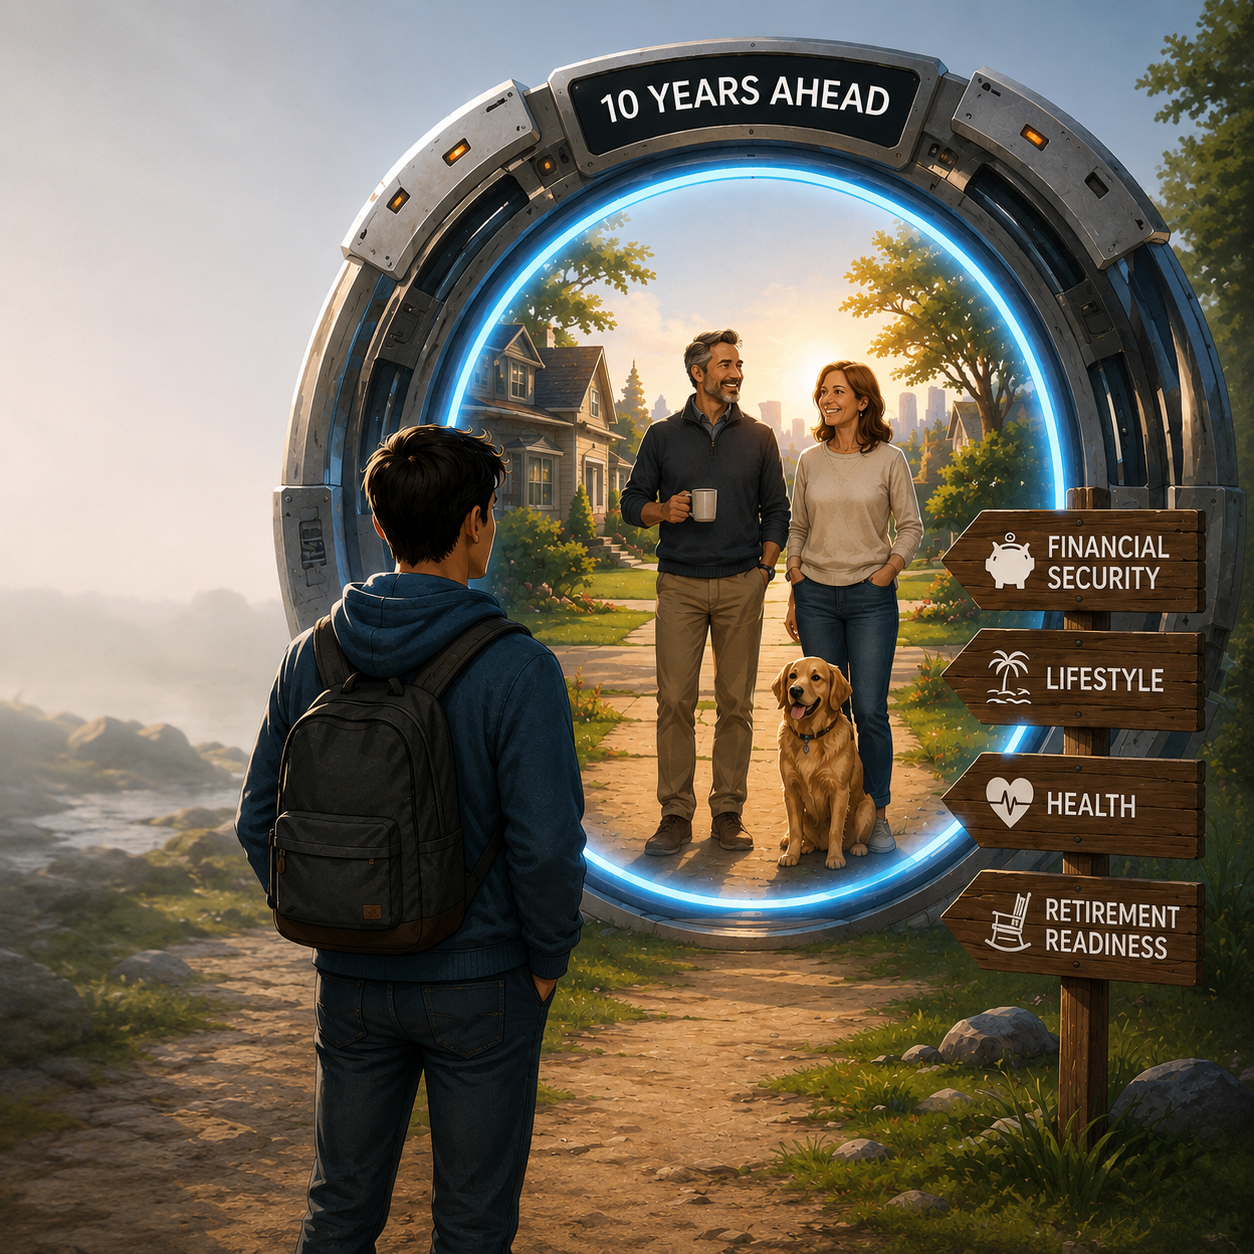
The Society Time Machine
One of the simplest psychological tools for thinking about your financial future is the “society time machine.” Find people who are about 10 years older than you, with similar education, income, lifestyle, and social environment. They may be coworkers or next-door neighbors. In many cases, they provide a surprisingly good preview of where you are…
-

Why Adults Regress Into Teenagers When Planning Finances
Grownups behave like teenagers when doing financial planning. In a bad sense. But it is difficult to blame them. After all, the situation is clear from any adult practical point of view. Somebody tells you what you have to do now to be safer in the future. But: The problem is that financial planning psychologically…